
At The O2 in Greenwich, August was the best month since the outlet centre opened in 2018. Retail sales there rose 11 per cent against a BRC national average of 0.7 per cent, food and drink spend climbed 16 per cent, footfall was up 5 per cent, and AEG credited the “social spending” that built up around Ariana Grande’s residency. The money consumers set aside for fun has not disappeared. It has simply become very particular about where it goes.
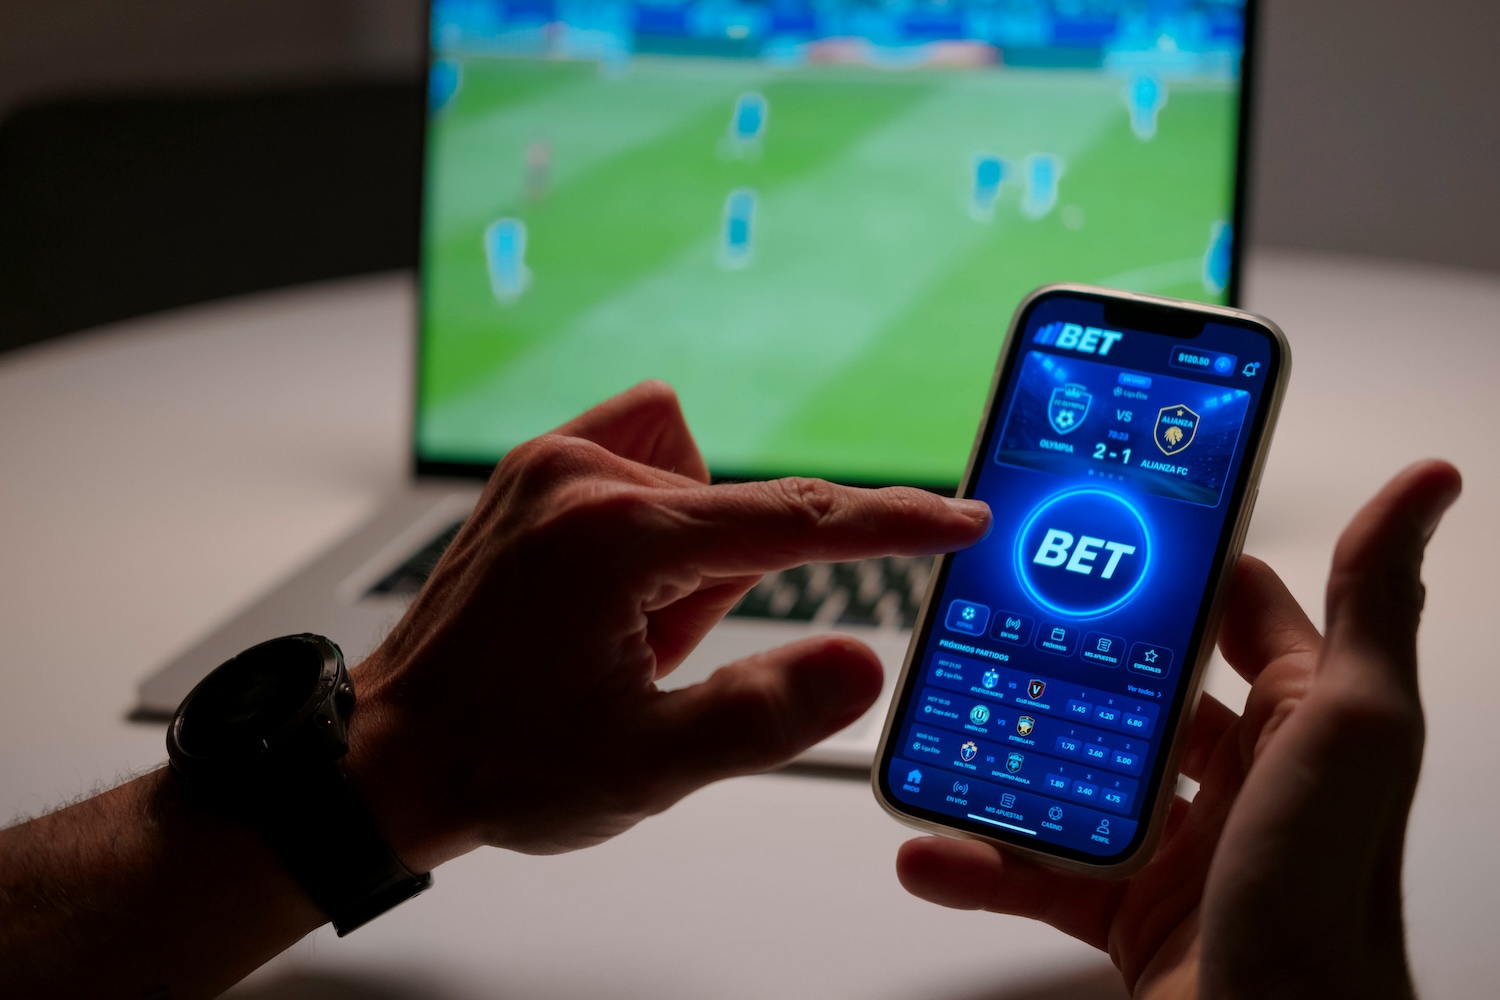
For more than a decade, one of those places has been online gambling, a market that regulation has now reshaped. Since April 2025, a single spin on an online slot has been capped at £5 for adults aged 25 and over, and £2 for 18 to 24 year olds, after a statutory instrument wrote the limit into every remote casino operating licence. Anyone who wants to see how operators look on the other side of those rules can check current rankings of new UK casino sites, which now score sites on how quickly they pay out, not just on their welcome offers. For retailers, the useful question is narrower: did capping the stake free up any of the consumer’s wallet?
What actually changed for players
The stake cap is the headline, but it sits on top of older rules. Autoplay on online slots has been banned since 31 October 2021, together with spin speeds faster than 2.5 seconds, so the cap was the second big intervention in game design rather than the first.
The newest layer arrived on 19 January 2026, when the Gambling Commission capped bonus wagering requirements at 10 times and banned promotions that combine products, such as a free bet that unlocks slot spins. Under the new ceiling, a £10 bonus can require no more than £100 of play before winnings can be withdrawn, where offers at 40 or 50 times were common before.
Operators are also carrying a heavier tax bill. Remote gaming duty rose from 21 per cent to 40 per cent of gross profits in April 2026, which squeezes the margin that used to fund generous promotions.
Spend has not left gambling
Here is the inconvenient part for anyone hoping for a windfall. The Gambling Commission’s industry statistics for 2025 to 2026, published on 17 September, cover April 2025 to March 2026, which is almost exactly the first year of the stake cap. Online casino games generated £5.7 billion in gross gambling yield over that period, £4.8 billion of it from slots. The remote casino, betting and bingo sector as a whole grew 6.9 per cent to £8.3 billion.
Quarterly operator data tells the same story. In January to March 2026, slots yield rose 12 per cent year on year to £773 million, spins rose 7 per cent to 25.1 billion and average monthly active accounts grew 6 per cent to 4.8 million. What did fall was intensity per sitting: spins per session dropped from 136 to 124, and yield per session from £4.01 to £3.82.
Put simply, the cap appears to have trimmed the size of the heaviest sessions while more people kept playing. That is a harm reduction result, and arguably the one policymakers wanted. It is not a transfer of household budget from the phone screen to the shop floor.
Where retail does feel it
The physical side of gambling is a different matter, and retailers can see it in their own streets. Great Britain had 5,617 betting shops at the end of March 2026, 208 fewer than a year earlier and the twelfth consecutive reporting period of decline. Each closure puts a unit back on the market, often on the secondary pitches and neighbourhood parades that landlords are working hardest to fill.
Leisure operators are among the tenants competing for that kind of space. British Land’s recent letting of 2,000 sq ft at The Barcode in Plymouth to Claw City, an all claw machine concept, shows the appetite for low stakes, in person play that sits comfortably inside a shopping destination.
Reading the consumer data
The wider figures suggest discretionary money is moving towards experiences faster than towards goods. Barclays card data for August showed total spending up 2.1 per cent year on year, entertainment up 5.9 per cent with transaction volumes up 10.7 per cent, pubs, bars and clubs up 2.7 per cent, and digital content and subscriptions up 7.2 per cent. The BRC and KPMG Retail Sales Monitor for the same month had total sales up 0.7 per cent, but non food sales down 0.8 per cent, with in store non food down 1.2 per cent and online non food down 0.2 per cent. ONS figures put August retail volumes 2.4 per cent above a year earlier, helped by food and drink.
Against that backdrop, online slots compete with retail for the same evening and the same phone rather than for the same basket. The £5 cap limits the worst sessions for the heaviest players. It does nothing to make a night in on the sofa less likely.
What retailers can take from it
The first lesson is about forecasting. Eighteen months of data show no gambling dividend at the category level, so it should not appear in anyone’s planning assumptions for the year ahead. Regulation that trims intensity tends to leave the underlying habit intact.
The second is about what is working instead. The O2’s August came from a packed live events programme and a food and drink offer that kept visitors on site for longer, both built around time spent with other people. That is the one thing a slot game on a phone cannot supply, and it is where the competition for leisure spending is being won.
The real test comes in the final quarter. Black Friday month and the run into Christmas will show whether the experiential pull of the summer survives colder weather, and whether the 54 per cent of consumers who told Barclays in August that they felt confident about spending on non essentials act on that in store or on a screen.